- 4539 Austin Bluffs Pkwy, Colorado Springs, CO 80918
- (719) 597 7823

Encumbrance: Definition, Example, and Types of Encumbrances
Online Casino Glory Have Fun With And Win Actual Money In Banglades
June 11, 2023Хоккей Онлайн Сегодня Прямые Трансляции%2C Результаты Вчерашних Матчей%2C Расписание На сегодня Завтра Хоккейная Статистика Чемпионат
June 13, 2023Content
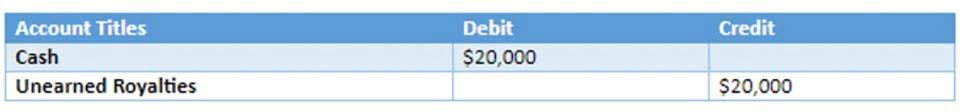
The first step encumbers newly entered purchase order line items into the General Ledger to help prevent overspending. After that, you unencumber the line items once they go into an Accounts Payable invoice for payment. During the initial pre-encumbrance phase, someone submits a request to reserve money for a future https://www.bookstime.com/articles/what-is-encumbrance-accounting payment. This money during this phase has been requested, but not yet approved for the purchase. Then, when that request is approved, a purchase order can easily be made for the exact amounts. When the encumbrance amount gets added to the general ledger, you can remove the payment from the pre-encumbrance amount.
Open encumbrances record the amount to be reserved from the unencumbered balance that is remaining to honor the commitments. For Purchase Order and Travel Authorization encumbrances, when the vendor or employee is paid, part or all of the encumbrance is released in accordance with that payment. The department will see a transaction that will appear under their Actuals (AC), separate from their Encumbrance (EX/IE/CE) debit/credit transactions. When you need to allot money for a future payment, such as when a purchase order is approved, the encumbrance account is debited.
Difference between Budgetary Control and Encumbrance Accounting
This is known in accounting as “pre-encumbrance,” meaning a projected but uncertain cost. Some businesses also have to project commission costs paid to representatives and independent contractors, which will vary with the amount of sales. Purchase order encumbrances are most commonly used in government accounting, but any organization can use the principle for budgetary control. Using encumbrance entries can serve as a general planning tool and can predict cash outflow. Encumbrance accounting, also known as commitment accounting, tracks anticipated spending to budgeted amounts.
If you view funds available for the amount type PTD for February, the February balances will not include the $40 available at the end of January. When you choose an amount type of YTDE, you can view cumulative amounts so the February balances will include the $40 available for January. They may be financial (for example, liens) or non-financial (for example, easements, private restrictions). Pre-encumbrances allow departments to further commit funds to facilitate financial management and are coded with balance type code PE. Encumbrance accounting should not be confused with the term encumbrance in real estate.
Lien
When tracking your transactions and expenses, it is crucial to reflect your cash flow on your general ledger accurately. Vital analysis, reports, and audits are based on the cash outflow and journal entries tracked by accounting, making accurate tracking much more than a simple general planning tool. An encumbrance, also called a pre-expenditure, is a method of tracking future period payments prior to the finalization of the project or the receipt of goods. Think of encumbrances as reserved funds to later pay pre-determined liabilities that will occur later. There are different encumbrance types, ranging from reserves for payroll to money set aside by budgetary control groups for things like contingency expenses. You can enter encumbrance journal lines if your data access set provides read and write access to the ledger, balancing segment values or management segment values.
In the future, when you pay that sum off, the encumbrance account is credited. Carry Forward rules 2 and 3 can be combined if you want to carry forward budget amounts equal to encumbrances plus funds available. Note that when combining these Carry Forward rules, they must be run consecutively in a specific order. First run Carry Forward rule 3, Funds Available, then rule 2, Encumbrances and Encumbered Budget.
Business is Our Business
Encumbrances can also be used to predict cash outflow and as a general planning tool. An important part of business finance and cash flow is making sure you understand how much of your available encumbrance accounting funds you can afford to place in reserve for the encumbrance account. Your reserve funds should be treated as if they don’t exist, and only dipped into for approved purchases or expenses.
- Many readers tell us they would have paid consultants for the advice in these articles.
- The accounting term encumbrance can sometimes be mistaken for real estate encumbrance.
- Encumbrance accounting, when properly implemented, allows for financial information to be seen and analyzed much quicker than a “budget to actual” accounting process.
- Rather than just looking at current transactions, this type of accounting encourages tracking upcoming expenses to help show a more detailed view of your cash flow.
- Note that General Ledger carries forward balances, not as period activity, but as beginning balances.
When you carry forward year-end encumbrances, the Carry Forward rule you specify determines the amounts to be carried forward. Note that General Ledger carries forward balances, not as period activity, but as beginning balances. You can also carry forward budget amounts equal to encumbrances and/or funds available. When you decide to carry cover encumbrances, check that all journal entries are correctly made and that all the balances you’re bringing forward are correct, since the balances you bring forward cannot be reversed.
What is an Encumbrance?
An example of Intellectual property encumbrance is “encumbered code”, software that cannot be freely distributed due to intellectual property rights. This distinction is particularly important during Fiscal Year-End Close because the Accounting Department and the UCI Budget Office only look at ‘Budget minus Actuals’ to determine if an account or fund is solvent. A negative easement restricts the title-holder, for example, by preventing them from building a structure that would block a neighbor’s light.
- Once the encumbrance is approved, the funds are no longer available for use in other transactions.
- If you do not carry forward encumbrances, you might want to cancel existing requisitions and purchase orders behind the encumbrances.
- During the initial pre-encumbrance phase, someone submits a request to reserve money for a future payment.
- In this document, the IT department can list the equipment they want to purchase and the vendor they intend to use.
- Are you interested in finding out more about how automation can empower your team and increase your visibility and expenditure control?
If you do not carry forward encumbrances, you might want to cancel existing requisitions and purchase orders behind the encumbrances. Please contact the offices listed below with questions about specific encumbrances or to request liquidation. A business or government can encumber funds in several ways and for several reasons.
